Nigeria’s financial technology market is entering a more demanding phase. Digital payments have become mainstream, fintech companies have expanded access to accounts and credit, and regulators are paying closer attention to the risks that accompany rapid innovation. Into this market comes Open Space Financial Services, a new Nigerian fintech that combines artificial intelligence (AI), open finance and ethical or non-interest finance.
The company was unveiled in Abuja on Tuesday with an ambition that extends beyond payments. Its proposition is to use technology to connect savings, investments, financing, payments and financial planning within one digital ecosystem while giving customers access to Shariah-compliant and conventional financial products.
The opportunity is substantial. EFInA’s latest nationwide Access to Financial Services survey found that 26 percent of Nigerian adults remained financially excluded in 2023, although formal financial inclusion had risen to 64 percent. The Central Bank of Nigeria (CBN) has separately identified financial inclusion as a central part of Nigeria’s economic development agenda.
Open Space enters a Crowded but Expanding Market
Open Space is not entering an empty fintech market. Nigeria has hundreds of digital finance companies competing across payments, lending, wealth management, banking infrastructure and merchant services. The CBN’s 2026 fintech report describes Nigeria as one of Africa’s leading fintech ecosystems, with Nigerian startups raising more than $520m in equity funding in 2024.
The scale of digital activity is equally important. Nigeria Payments Report 2025 said the country processed ₦1.56tn in electronic payment transactions in the first half of 2024 alone.
That means Open Space will need to offer more than another digital wallet. Its differentiation is the combination of AI with ethical finance.
Chief executive Titus Ikeh said the company wanted to move finance beyond transactions and towards helping customers make decisions, build businesses, acquire assets and accumulate wealth. “We did not set out to build another platform,” he said at the launch.
That positioning is commercially sensible. Payments can generate volume, but deeper financial relationships can generate recurring revenue through savings, investment, financing, insurance and wealth-management products.
AI is Becoming Financial Infrastructure
The more interesting part of Open Space is its proposed use of artificial intelligence.
Open Space says AI and machine learning will support customer analytics, behavioural analysis, anomaly detection, portfolio monitoring, predictive insights and personalised financial experiences. Its technology architecture is also designed to automate onboarding, know-your-customer verification, affordability assessment, payment collection and customer service.
This comes as Nigerian fintechs are increasing their use of AI. The CBN’s fintech research found that fraud detection is the leading AI application among Nigerian fintech companies, followed by areas including customer service and credit assessment.
The economic value is straightforward. AI can process large quantities of customer and transaction data faster than conventional systems. It can identify unusual behaviour, improve risk assessment and help platforms tailor financial products to individual circumstances.
For consumers, the practical benefit could be better budgeting and financial planning. For businesses, AI could improve cash-flow analysis and access to working capital. For fintech operators, automation can reduce the cost of serving customers.
But AI also creates risks. Poor-quality data can produce poor decisions. Automated credit assessment can reproduce existing biases. Financial platforms must therefore combine AI with strong governance, explainable decisions, cybersecurity and consumer protection.
Ethical Finance gives Open Space Another Market
Open Space’s second differentiator is ethical or non-interest finance.
The company says its model will use structures such as Murabaha, Ijarah, Mudaraba and Diminishing Musharakah. These models can finance assets, investments and business activities without using conventional interest-based lending.
This is increasingly relevant in Nigeria. The CBN has been developing the country’s non-interest financial market, including non-interest asset-backed securities and the CBN Non-Interest Note. In February 2026, the regulator also approved a non-interest banking window for the Bank of Industry.
Open Space is therefore entering a segment that already has regulatory and institutional foundations.
The commercial proposition is broader than serving Muslim consumers. Ikeh argues that transparency and clear financial relationships appeal to customers regardless of religion. That is potentially important because ethical finance can compete on principles such as asset backing, disclosure, risk sharing and responsible financing rather than religious identity alone.
The company’s ethical-finance adviser, Muhammad Zubair Mughal, brings international Islamic-finance experience to the proposition. Open Space says he has worked across more than 40 countries with institutions including the World Bank’s IFC and the Islamic Development Bank.
From Wallets to Productive Capital
The strongest part of the Open Space proposition is its attempt to connect financial access with productive economic activity.
Its platform includes OpenMarket for informal micro-lending and OpenFactoring for businesses seeking early payment against outstanding invoices. The company says OpenFactoring can advance up to 80 percent of eligible invoice value, potentially helping businesses overcome the long payment cycles that frequently constrain working capital.
This is where fintech can have a wider economic effect.
A market trader does not only need a payment account. She may need working capital. A small manufacturer may need machinery. A farmer may need financing before harvest. A growing business may need cash while waiting for customers to settle invoices.
Financial technology becomes more useful when it connects those needs to capital efficiently.
Open Space’s CTO, Ololade Otayemi, told THISDAY that the platform would use a “Single Customer Financial Core” incorporating customer information, wallet and investment engines.
The architecture could reduce the need for customers to maintain separate financial identities across multiple products. That creates a more coherent financial profile and gives AI more data with which to provide personalised services.
The African Opportunity is Larger
The opportunity extends beyond Nigeria.
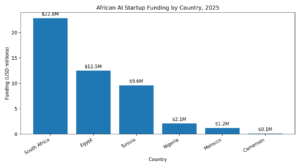
Nigeria is already one of Africa’s largest fintech markets, and the country has developed payment infrastructure that can support regional expansion. The European Investment Bank has described Nigeria, South Africa, Kenya and Egypt as the four markets hosting about 70 percent of sampled African fintech operators and attracting about 80 percent of fintech funding.
African fintech funding also remains concentrated in financial services. Partech reported that African fintech companies raised $1.49bn in equity and debt funding in 2025, making fintech the continent’s largest funded technology sector.
For Open Space, expansion could come through products that address common African problems: informal commerce, limited credit histories, weak cash-flow visibility and demand for alternative financing structures.
AI could make that model more scalable. Instead of relying entirely on physical branches or large operational teams, digital systems can analyse transactions, automate routine processes and deliver financial guidance through mobile devices.
The Real Challenge is Trust
The difficult question is not whether Open Space can build an AI fintech platform. It is whether it can earn sustained customer trust.
Nigeria’s fintech market has already demonstrated that consumers will rapidly adopt digital financial services. The next stage requires reliability, transparent pricing, strong security and responsible use of personal data.
The IMF has noted that fintech has helped increase access to financial services in Nigeria, with 74 percent of adults having access to financial services in 2024, while warning that rapid digital growth also increases fraud risks.
Open Space therefore faces a demanding execution agenda. It must prove that AI improves outcomes rather than simply providing a marketing label. It must demonstrate that ethical finance products can scale efficiently. It must also show that customers can understand the products before committing their money.
If it succeeds, Open Space could occupy a useful position between fintech, AI and ethical finance. Its larger opportunity is not simply to create another financial app. It is to build a system that connects financial intelligence with access to capital, asset ownership and wealth creation.
That is a much harder proposition than payments. It is also potentially much more valuable.
About Open Space
Open Space Financial Services is a Nigerian AI-powered neo-fintech building a digital ecosystem that combines conventional and ethical or non-interest finance with open banking, commerce and everyday services. Its OpenPay financial engine supports savings, payments, investments, financing, wealth creation and personalised financial experiences. The company also offers products including OpenMarket, OpenFactoring, OpenSave and OpenInvest, while developing Murabaha and Mudaraba solutions. Open Space says its mission is to empower humanity through disruptive innovation and trust capital, while its vision places people at the centre of financial and lifestyle innovation. Its headquarters is in Abuja, with offices in Lagos and Toronto.